You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
Hey Nerds: Blockchain
- Thread starter zeke
- Start date


CH1
The Artist Formerly Known as chiggins.
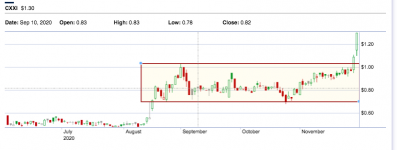
That's why I bought CCHW. It's trying.
Yeah, looks like it escaped the box and is now testing it from above, which is perfectly fine

Preston
MBow30 alt account
Mickey Mouse shitInteresting...it looks like CBII is still using its old US ticker.... CBIIF even with the new name Skylight Health Group....up 13%
Preston
MBow30 alt account
Btw CB2 Insights put out some guidance on their NR today.
Assuming the $20m is a proforma run rate, which is about what I expected. Still lacking organic growth but the acquisitions are clearly providing value as they've all been profitable operations before the acquisition. And then there's the likelihood of optimizing their efficiency moving forward, leading to further profitability and (hopefully) growth. Early days but so far it looks like they did their homework on their acquisitions. Got some great deals.
And they have a real healthy cash position at around $10 milly.
The Company has already demonstrated its ability to target, qualify and acquire with its two most recent transactions in October and November 2020 and a third deal already announced and set to close early 2021. On an aggregate basis, the three transactions will add an incremental expected $5 million to the current run rate. The Company is on track to achieve a $20 million run rate by the end of 2020.
Assuming the $20m is a proforma run rate, which is about what I expected. Still lacking organic growth but the acquisitions are clearly providing value as they've all been profitable operations before the acquisition. And then there's the likelihood of optimizing their efficiency moving forward, leading to further profitability and (hopefully) growth. Early days but so far it looks like they did their homework on their acquisitions. Got some great deals.
And they have a real healthy cash position at around $10 milly.
Preston
MBow30 alt account
This is why we bet on that management. Some smart mother fuckers there.I like that they have zero debt and 10M in the bank


Preston
MBow30 alt account
Won't sleep till GTII gets ATHs. Just under 20% to go. God damn 2018 Leon Cooperman hype move when the stock was EXTREMELY low float with mostly locked up shares making it hard on them.
Wouldn't shock me if it doesn't come till next earnings in March assuming no SAFE before then.
Wouldn't shock me if it doesn't come till next earnings in March assuming no SAFE before then.
Preston
MBow30 alt account
TRUL was a late bloomer. No one really expected Florida to show that kind of growth and no one expected Kim to absolutely control the state like she has. GTII was always seen as a top tier MSO with great assets so it had its big run in 2018 when Leon Cooperman pumped it to crazy heights. Though at the time GTII along with the other MSOs were barely posting any revenues. It was entirely a hype move based on speculative upside.I would have thot GTII would have outperformed TRUL....but perhaps all that tv work Kim does benefits the stock
This was the quarter that took them from ~$8 to $32.50ish in like 2 weeks. Just 2 years ago. Feels like a lifetime! Was mostly a pump and dump. Huge upper wick and never really came close to those levels again until recently.
- Second quarter 2018 revenues increased 291% year-over-year to $13.6 million. Quarter-over-quarter revenues increased 25%.
- EBITDA1 was a negative $4.7 million for the quarter. Adjusted EBITDA1 which excludes non-cash and one-time expenses related to the Bayswater reverse takeover transaction (“RTO”) was $0.5 million.
- GTI’s net income was $0.4 million, up from a loss of $1.6 million in first quarter 2018.
- Current assets totaled $128.4 million as of June 30, 2018, including cash and cash equivalents of $112.7 million.
- The Company has approximately $7.9 million of total debt, $1.4 million of which is due within 12 months.
- The Company raised net proceeds of $61 million through a brokered and non-brokered private placement in connection with the RTO of a Canadian public company.
At the same time TRUL was actually doing fine. I believe they were kind of profitable, but no one even considered a single state operator to be in the same league. Revenue wasn't growing close to the same rate either. So they were realllllllllllllllly cheap 2 years ago.